Lender makes mortgage offers valid for 9 months, up from 6 months - brokers "hope" it will start a trend

ended 28. October 2026

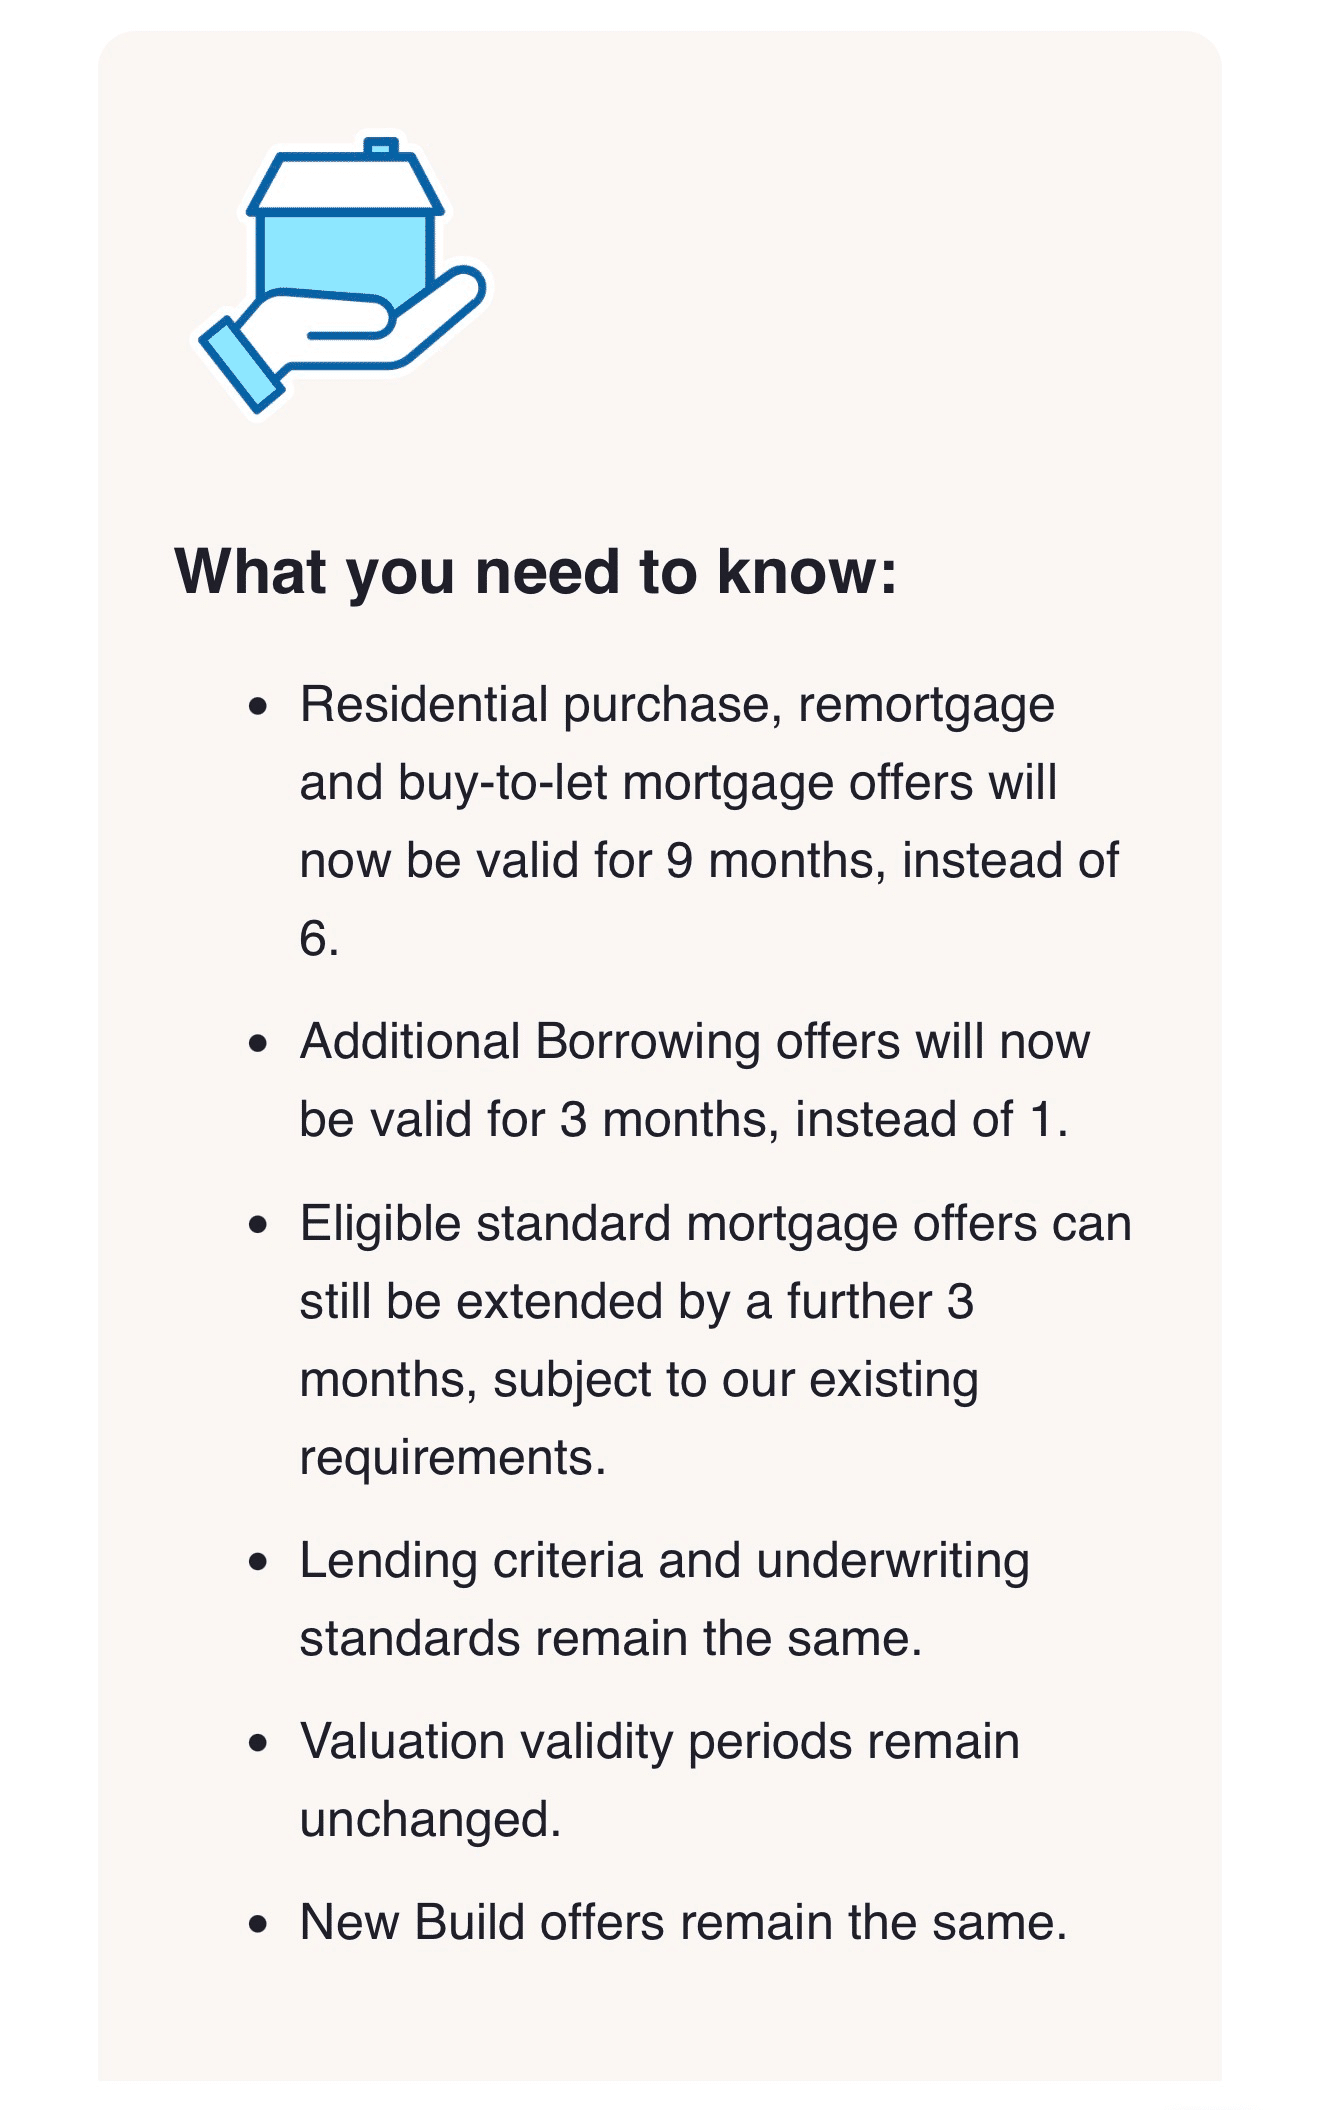
Skipton today announced the extension of their mortgage offer validity to nine months from six, potentially allowing clients to secure a new rate nine months before their current rate ends. 

Is this the start of a new trend from lenders to try and secure borrowers earlier?

How soon is too soon?

Could it be cost for lenders if rates rise over the nine months period?
Questions for Newspagers

  1. Will this be the start of a trend?

9 responses from the Newspage community

Copy all

Story Source
Copy

The really interesting part of this change is not purchases, it is remortgages. A nine-month offer potentially allows someone to secure a new mortgage long before their current fixed rate ends, giving them protection if rates rise while still leaving time to review the market if pricing improves.

In effect, a longer offer period starts to act like insurance against future rate rises. That is very attractive for borrowers, but it creates an interesting challenge for lenders because customers are most likely to keep the offer if rates rise and look elsewhere if rates fall. I will be interested to see whether other lenders follow Skipton or decide nine months is simply too long to commit to today’s pricing.
Copy

Pro
Rohit KohliVerified
Director at Senior Mortgage Adviser - Residential & Commercial
iContact details are shown to logged-in members. Log in
I have mixed feelings about this. From a client point of view it’s potentially really helpful. If you’re remortgaging, in particular, you could lock in a deal at today’s rates nine months before your current one ends, and plenty of borrowers will like that certainty.

But the house buying process in England is already flawed and far too slow. My concern is that longer offers become a reason to take longer, rather than a push to get deals through faster and more efficiently. If other lenders follow suit, that risk grows.

As for cost, a lender holding a rate for nine months is taking a bet on where rates go. If they rise, those offers are on the books at a lower rate, and that has to be priced in somewhere. If rates fall, borrowers can often look again, so the lender may lose the business anyway.

Nine months gives people breathing space. It shouldn’t become an excuse for the system to move even slower.
Copy

Pro
Justin MoyVerified
Managing Director at EHF Mortgages
iContact details are shown to logged-in members. Log in
It's a good opportunity, and may be something a few lenders will look to introduce too. Ideal for those looking to secure a new mortgage deal up to 9 months in advance of their renewal, especially in a turbulent market, giving some early peace of mind. The downside is that it adds another 3 months to the routine checking of rate changes, especially when rates do start to fall, and the additional administration involved with that process. But for those buying, having a 9-month offer will give more than enough time to complete their purchase, without the need of a extension.
Copy

Pro
Tracey DixonVerified
Buy-to-Let Mortgage Specialist & Owner at Pure Mortgage and Protection
iContact details are shown to logged-in members. Log in
A nine-month mortgage offer is welcome, but borrowers need to know which parts of their application have the same shelf life.

Skipton’s announcement says valuation validity periods remain unchanged. That detail matters: a longer offer does not automatically mean every part of the mortgage application remains valid for nine months. Clear communication will be essential to avoid replacing one deadline with another surprise.

For remortgage customers, the extra time could be valuable for planning household budgets and organising the switch when their existing deal ends. However, securing an offer should begin a period of regular review, especially if rates or circumstances change.

I would welcome other lenders following, provided the flexibility comes with clear conditions. The measure of success should be how many borrowers reach completion with a suitable deal and less stress, rather than how early lenders secure an application.
Copy

Pro
Samuel Mather-HolgateVerified
Managing Director & IFA at Mather and Murray Financial
iContact details are shown to logged-in members. Log in
This is an absolutely brilliant move by Skipton and exactly what the mortgage market needs. Property chains are moving at the speed of a funeral procession, with buyers stuck in limbo for months while transactions crawl towards completion. The last thing anyone needs is their mortgage offer expiring just as the removal vans finally arrive.

Nine-month offers give borrowers breathing space and remove another unnecessary obstacle from an already struggling housing market. I fully expect other lenders to follow suit, particularly as competition for borrowers intensifies.

Yes, lenders risk being caught out if funding costs rise, but that’s their risk to manage. For borrowers, securing a rate nine months early could be a financial lifeline. Frankly, in this market, six months can disappear before the solicitors have finished arguing over the garden fence.
Copy

Pro
Nouran MoustafaVerified
Practice Principal & IFA at Roxton Wealth
iContact details are shown to logged-in members. Log in
I think this could be the beginning of a new battleground between lenders. They're no longer competing just on rates, but on how early they can secure a borrower's business.

Nine-month offers are attractive because borrowers can protect themselves against potential rate increases without waiting until the last minute.

But there's a commercial risk for lenders. If rates rise significantly, they're committed to honouring existing offers, subject to their terms. If rates fall, borrowers may switch to cheaper deals.

It's an interesting imbalance, and lenders will need to price that risk carefully.

My concern is borrowers confusing early preparation with committing too early. Securing a rate nine months ahead can be sensible, but only if the mortgage remains competitive and suitable.

The real winner won't necessarily be the lender offering the lowest rate today. It could be the one giving borrowers the longest protection against tomorrow's uncertainty.
Copy

Platinum
Elliott CulleyVerified
Director at Switch Mortgage Finance
iContact details are shown to logged-in members. Log in
This is a positive move by Skipton and hopefully more lenders will follow their lead. Although most mortgages should be sorted with 6 months, there are a few that go beyond this timeframe and this extension eases that pressure, espcially in the current climate, where clients who don't complete would see large increases to monthly payments as rates have increased. This should not be a difficult change for lenders to make as a few already offer extended offers on new build properties.
Copy

Plus
Louis MasonVerified
Content and Communications Director at Oportfolio Mortgages
iContact details are shown to logged-in members. Log in
I wouldn't be surprised if other lenders follow Skipton's lead. Mortgage lenders are competing not just on price anymore, but on how early they can get borrowers through the door. In an unpredictable rate environment, offering nine months of certainty is an attractive selling point, and it gives lenders an opportunity to secure business before competitors even enter the conversation.

However, there's a difference between securing a mortgage early and committing to one too early. Nine months is a long time in the mortgage market, and a deal that looks competitive today could be considerably less attractive by next summer. The key is retaining the flexibility to review the rate before completion.

There's also a commercial gamble for lenders. If funding costs rise significantly during those nine months, an earlier offer could become less profitable, although lenders will manage that exposure through their pricing and hedging strategies.
Copy

Plus
Thomas BoughtonVerified
Founder at Artillium Real Estate Finance
iContact details are shown to logged-in members. Log in
It's a step in the right direction for those lenders who value retention as it makes it easier and more convenient for borrowers to remain. However, I don't think we will see all lenders adopt this stance as not all lenders do value retention nearly as much as people think.

We've seen a trend with some High Street Lenders over the past few years who consciously price their existing client / product transfer rates above remortgage rates in comparison to alternative lenders which force borrowers to refinance their existing mortgage to a new lender.

Those lenders who truly value retention should adopt this stance and it's good timing from Skipton in light of the current market.

Again, it highlights the importance of using a broker who acts in your best interest. When rates come down, we're the first to know but will a lender do the same for you if you go direct? Are 'direct to lender' borrowers made aware it's possible to make multiple interest changes prior to a new rate going live?