HSBC Latest Lender to Offer up to 6.5 x Income Mortgages

ended 04. November 2025

HSBC has announced an enhancement to their affordabilty assessment :
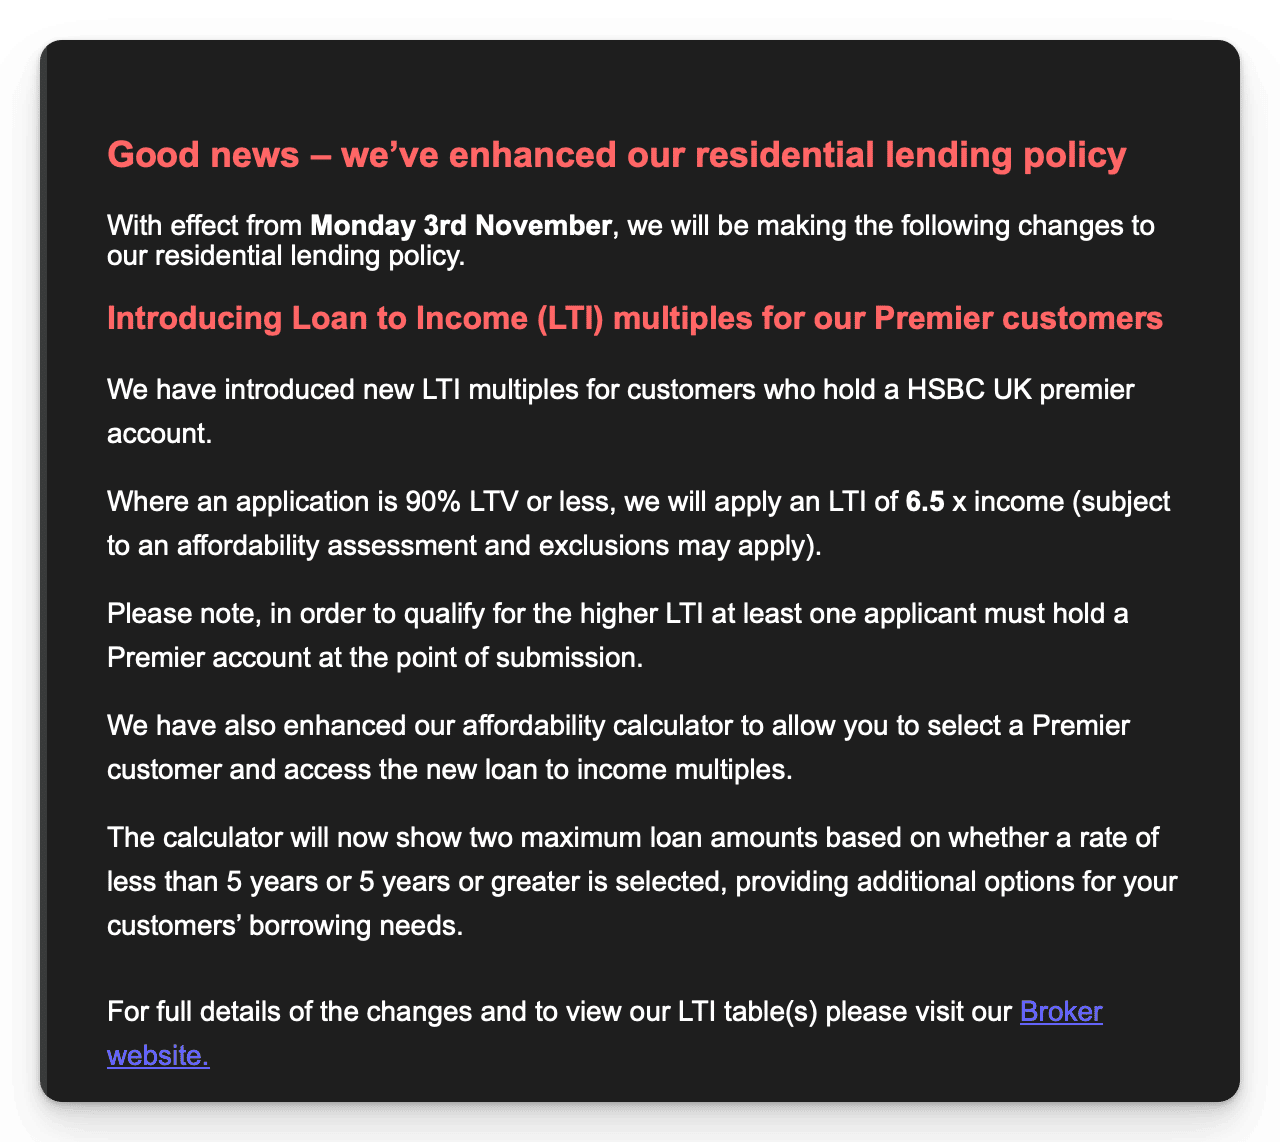
This is exclusively for HSBC Premier Account Holders, with the enhancement at its fullest for 5-year fixed deals.

Is this a good move for loyal HSBC borrowers? Do Brokers need to ensure they ask about a client's banking arrangements before they talk figures? Will people look to tactically take bank accounts with lenders who offer loyalty schemes for mortgages?

Plenty of questions for your comments - Tuesday AM latest for early article
3 responses from the Newspage community

Copy all

Story Source
Copy

Pro
Justin MoyVerified
Managing Director at EHF Mortgages
iContact details are shown to logged-in members. Log in
This may be the first affordability improvement that will benefit the current account holders of that lender, with Premier Account holders in line to receive the greatest opportunity here. With banks holding huge amounts of information and knowing the spending patterns of their account holders, this move can utilise that knowledge and ensure that those borrowing up to 6.5x income can afford to do so. This move will be important in those more expensive areas around London and the South East, so I would imagine that HSBC will be selling a lot of their Premier Account packages over the next few months. More lenders with greater affordability options, but with a loyalty twist that will interest other High Street lenders into adopting, perhaps.
Copy

Pro
Ranald MitchellVerified
Director at Charwin Mortgages
iContact details are shown to logged-in members. Log in
HSBC’s move to enhance affordability for Premier customers is a progressive step that pushes them ahead of much of the competition at the vanilla end of the market. It rewards loyalty and could allow borrowers to access larger loans, particularly on 5-year fixed deals where affordability is strongest. But let’s be clear, this is also a clever play to attract and retain high-value current account customers. HSBC’s Premier status isn’t open to everyone. To qualify, you’ll typically need a household income of £75,000 or more or hold at least £50,000 in savings or investments with the bank. So, this is as much a tout for their Premier banking arm as it is a lending enhancement. If this triggers an ‘affordability war’ between lenders, consumers could benefit. But it’s crucial that any competitive push remains grounded in stable, responsible lending. We’ve learned enough from history to know what happens when affordability is stretched too far.
Copy

Pro
David StirlingVerified
Independent Financial Adviser at Mint Wealth
iContact details are shown to logged-in members. Log in
For clients who are HSBC Premier Account Holders, this enhancement, particularly on 5-year fixed deals, could be a real advantage. From an advisory standpoint, it’s going to be essential to start asking about a client’s banking arrangements early in the conversation, as loyalty-linked deals can influence the most suitable mortgage options. We may also see clients strategically opening or maintaining accounts with lenders that offer loyalty incentives, so it’s worth discussing the potential benefits of these schemes when planning their mortgage planning.